The Real Financiers of Eswatini Property Are Not Banks
Author
Mlamisi Mdluli
Contributor
Published
Reading time
Stokvels, family contribution schemes, and informal savings groups quietly finance more Eswatini homesteads than mortgage statistics ever show.
How property actually gets paid for
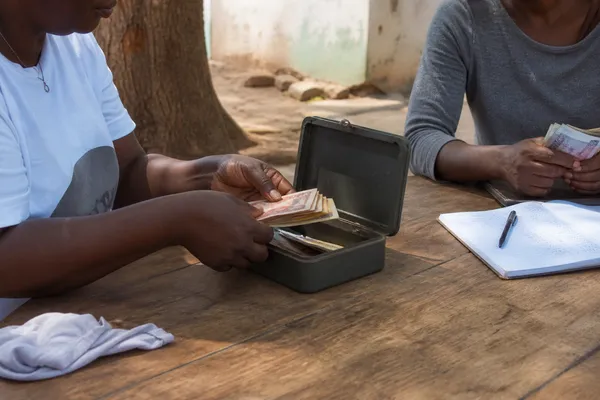
Walk into most bank branches in Eswatini and ask how the average home gets financed, and the answer will usually revolve around mortgages, salaries, and credit checks. Walk into most communities instead, and a very different financial system reveals itself: one built on rotating savings clubs, or stokvels, family contribution schemes, burial societies, and other informal savings groups that sit alongside—and often ahead of—formal lending in everyday life.
These groups rarely make headlines and almost never appear in a bank's annual report, yet their influence on how Eswatini families acquire and improve property is significant. A group of colleagues pooling a fixed amount each month, a family collecting contributions ahead of a relative's wedding or funeral, a savings club rotating a lump sum among its members each cycle—all of these arrangements end up, sooner or later, funding a roof extension, a deposit on land, or the materials for the next phase of a homestead. Property does not always wait for a bank's approval. Often it waits for a stokvel payout instead.
Burial societies and similar pools belong to the same informal money culture; the path into bricks and land more often runs through stokvels and family contribution schemes that members deliberately aim at a build or purchase.
Why informal groups work where credit scoring does not
There is real financial logic behind why these informal structures thrive where formal lending does not always reach. Trust between members replaces collateral requirements. Peer accountability replaces credit scoring. A missed contribution is noticed immediately by people who know the defaulter personally, creating a form of social pressure that many formal institutions struggle to replicate through paperwork alone. For families without payslips, formal employment, or a long credit history, a stokvel can be the only realistic path to raising a meaningful sum of money for property, and it is a path many families have used successfully for generations.
The ceiling of trust and discipline
This is not to suggest that informal finance is without weaknesses. These arrangements depend heavily on the integrity of whoever manages the funds, and disputes over missed payments or mismanaged pools are not uncommon. Growth is also naturally limited by how much members can contribute, meaning larger property ambitions, such as commercial developments or significant renovations, often outgrow what an informal group can realistically provide. There is a ceiling to what trust and discipline alone can finance.
Design with stokvels, not against them
What deserves more attention is the space between these two systems, the formal and the informal, and how little conversation currently happens between them. Financial institutions and property professionals in Eswatini have an opportunity to design products that work alongside stokvels rather than in competition with them, whether through savings-linked accounts, group lending models, or simple financial literacy support aimed at helping these groups manage larger sums more securely as their ambitions grow.
Treating informal savings culture as a gap to be closed misses the point entirely. It is not a gap. It is infrastructure, built by ordinary people, that has quietly financed property across this country longer than the modern mortgage market has served most households.
Understanding that is the first step toward serving Eswatini's property market as it actually functions, rather than as textbooks assume it should.